Securing Family financial futures
One of the smartest things I have done since retiring is to learn about financial literacy. After being a direct mail printer for the last forty years I thought I knew how to manage money. After all, I had a house that was almost paid for, I had a wife, family, and three cars. I had several collections of valuables and hobbies to keep me busy the rest of my life. That should have been enough for me to be content. But I still wanted more.
I still had a few items on my bucket list that I still wanted to be able to check off that list while I still had my health. Success, in my mind, was how much money I had access to. Even though I have been blessed with good health, I still felt I needed to accomplish more.
I did not want to just become a couch potato and watch TV for the rest of my days when I retired. My wife told me that I had earned it. I did not need to work. I should be happy in my retirement years not doing anything.
This was not enough for me, though. I had been working with my hands since I was 16 years old, and old habits are hard to break. At 68 years old, you would think that slowing down would have been a good thing. Now I knew hard physical labor was out of the question. I’m no longer bullet-proof. But deep down I felt I needed to do more.
Getting back to my bucket list, I have a new desire in helping people avoid the mistakes I made financially. I want their retirement years to be free from money worries. Now that I have been educated in financial literacy, I want to be a blessing to others by passing the torch, so to speak.
“The biggest expense you’ll ever have isn’t your house or your car. It’s what you don’t know about money”
Let me ask you a simple question.. “If your paycheck stopped today, how long could you continue living the way you do now?” For most people, the length of time would be very short. What could you do to stretch out that length of time to not have to worry about that next paycheck?
Financial Literacy isn’t about becoming rich – “it’s about making sure your money serves your family instead of your family serving money.”
A New Investment Strategy
I’m not here to sell you anything today. I’m here to share information that most of us were never taught in school – information that can change the financial future of your family. Let me ask you another question: “If someone had shown you a better way to build wealth, reduce taxes, and protect your family years ago, would you have wanted to know?”
One of the things that financial literacy has taught me is consistent savings along with compound interest leads to wealth. One of the many financial products today is the Indexed Universal Life, or IUL, for short. I may have said this before, but had I used the 1031 exchange to reinvest my 401(K) into an IUL, I would have created a retirement account that would provide income for life!
A goal
The first commercially available IUL policy was introduced by Transamerica Occidental Life Insurance Company in January 1997. It was a life insurance policy that allowed the interest being earn to mirror the S&P Index. If the S&P had a positive return that month, the life insurance policy would reflect that positive growth. Another key component of the IUL is when the Index fell in value the IUL would not fall, it would just have a “0” percent growth for that month.
This is one of the best growth strategies anywhere because your money not only grows along with the Index it is tied to but it is also protected from falling! Some months your money will grow up to the cap rate, whatever the policy is set to. The cap rate is a ceiling, or maximum amount your policy can grow. An example is if the cap rate is 13%, if the Index rises 18%, your policy only gets credit of 13%. By the same token, if the Index falls to a negative 3%, Your policy is only credited with a 0% growth for the month.
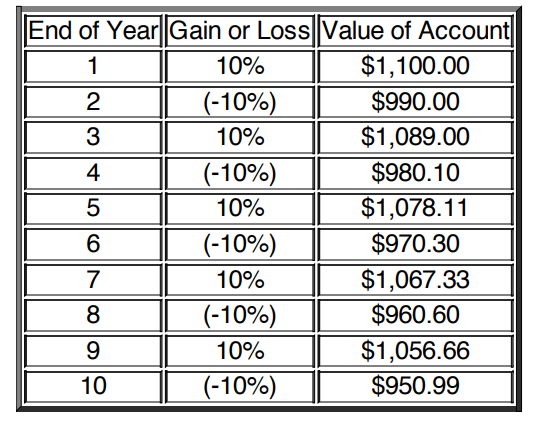
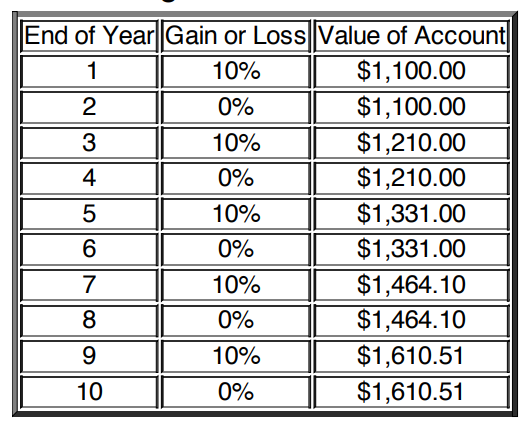
As in the two charts below, the top chart shows your money growth in the stock market with its up and down swings and what happens to your money. In the bottom chart, this shows the results of your money in a protected account like the IUL where your account never loses money.
Text content
The differences in the results of the stock market index downswings was something my financial advisor never explained. I had always thought that once the stock market recovers that my money would start growing again. Boy, was I wrong! This is the main reason I became a financial advisor – to educate people about the advantages of life insurance.
As a financial professional I am so excited to provide this protection to everyone. Stay tuned for new developments coming soon..